Floor · September 14, 2026 · 7 min
The 10-year hit 5%. Pick up the phone.
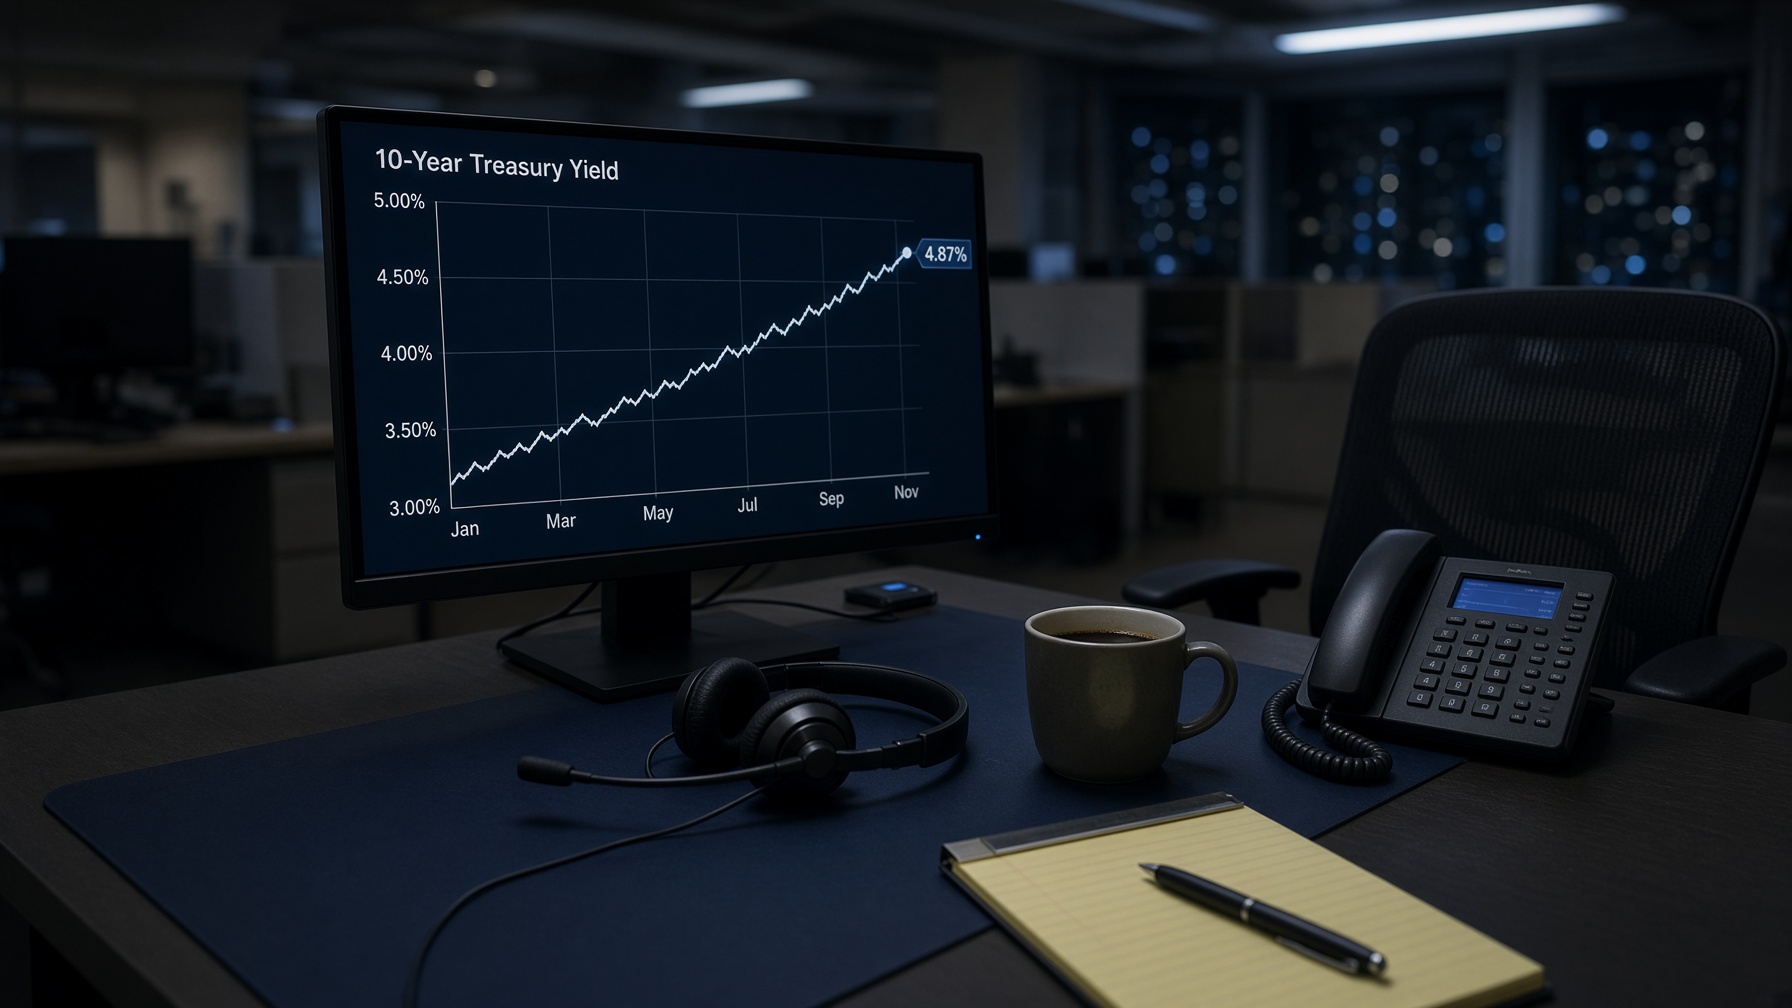
The 10-year Treasury just tagged 5% and half the floor is staring at a chart like it is a eulogy. Headsets come off. Coffee station fills up. Somebody says “nobody is refinancing at these rates.” Somebody else says they are waiting for the Fed. Production dies before lunch, and it was not the bond market that killed it. It was the attitude.
I am going to give you just enough on how this works so you sound like an adult on the phone. Then I am going to tell you the part nobody wants: the rate does not fund your month. You do.
What the 10-year actually is
The 10-year Treasury is the yield the market pays to lend the U.S. government money for ten years. Bond prices and yields move opposite. When people pile into bonds, the price goes up and the yield comes down. When they sell, the price drops and the yield jumps. That 5% number is the yield, not a mortgage coupon.
Mortgage rates watch it because a 30-year fixed loan is a long pile of cash. Investors who buy mortgage-backed securities can also buy Treasuries. If the 10-year pays more, those investors demand more from mortgages too. That is why your lock desk twitches when the 10-year runs.
Mortgage rates are not the 10-year
A 30-year rate is roughly the 10-year plus a spread. In that spread lives the mortgage-backed security, the guarantee fee, servicing, credit risk, and what your shop needs to make on the loan. It is not one-for-one. The 10-year can jump 10 basis points and your rate sheet might barely move. It can sit still and your sheet can still get worse because the spread blew out.
Borrowers do not buy a yield. They buy a payment, a term, cash in or cash out, and whether they trust you. If you lead with “rates are high,” you taught them to wait. If you lead with the file in front of you, you might still take an application.
Staring at 5% is a production problem
Here is what I see when the 10-year prints a scary number. Loan officers refresh CNBC. They text the group chat. They tell the last two people who picked up that “now might not be the time.” They burn a live conversation to sound smart about bonds. Then they sit in the negativity until the board looks empty and they blame the market.
Negativity is a habit. It feels like research. It is not. It is how you talk yourself out of the only activity that still works when the tape is ugly: conversations. The LO who is still dialing while you explain duration is going to take the apps you decided were impossible.
- People still buy houses when the 10-year is at 5%.
- People still refinance when the payment, the cash, or the term is the real problem.
- People still have a 7% second, a balloon, a PMI, a divorce, a shop they hate.
- None of that cares that you were in a mood about Treasuries.
Rate is not the job
Your job is to sell. Period. You sit down, you interrupt people, you find out if you can help, and you ask for the business. The 10-year does not do any of that. A positive attitude does not mean you lie about the payment. It means you do not poison the call before it starts.
Walk in like the day is winnable. If the rate sheet is worse than last month, say so like an adult and get back to the file. Payment. Term. Cash. Next step. That is the conversation. “Waiting for a cut” is not a pipeline. It is an excuse with a headline.
The only move
You cannot control the 10-year. You cannot control the Fed. You cannot control the coffee-station economist who has not taken an app in two weeks. You can control your mindset and the next dial. That is it.
Put the chart away. Headset on. List in front of you. Four minutes. A dated next step. Do it again. The LOs who fund in a 5% 10-year tape are not magicians. They decided the market was not allowed to run their attitude, and they picked up the phone.
The playbook and the warm lead script are in the free closer kit.